Wall Street traps and on-chain liquidity expose retail perpetual trading risks
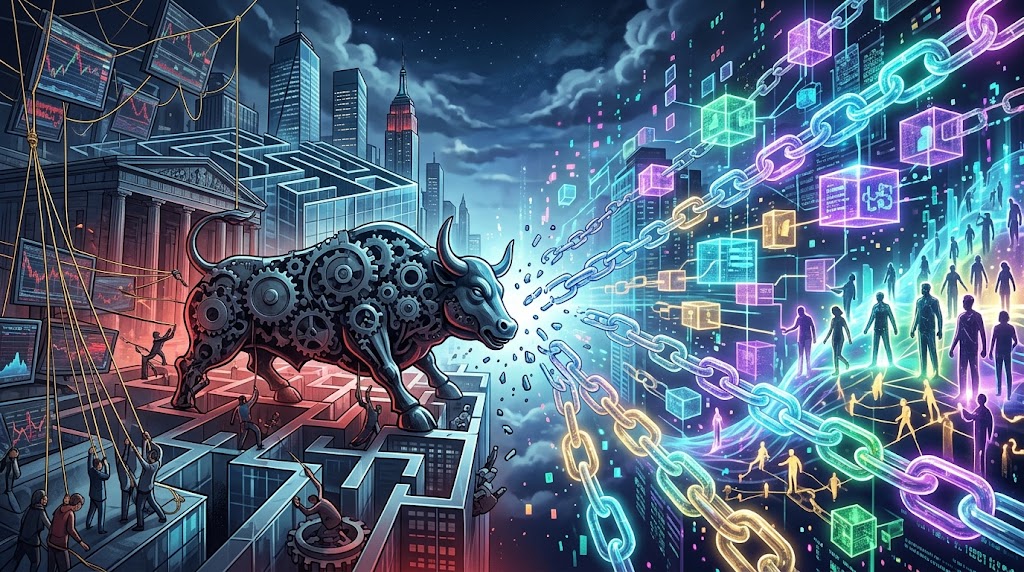
The traditional public listing model faces an institutional crisis that Jeff Yan, founder of Hyperliquid, characterizes as structural extraction: private equity rounds absorb the exponential growth phases of emerging companies, leaving initial public offerings as liquidity mechanisms where venture funds offload overvalued equity onto retail participants.
In direct opposition to this dynamic, distributed architectures offer fully audited on-chain order books and continuous settlement designed to remove centralized financial gatekeepers.
This infrastructure is not operating on the periphery, but directly challenging global liquidity channels. Regulatory studies published by the Financial Stability Board reveal that decentralized execution venues now maintain sufficient volume depth to influence macro capital flows. In defensive adaptation, legacy operators like Intercontinental Exchange have advanced tokenization partnerships and digital infrastructure to support continuous asset transfers throughout the calendar year.
The transition toward decentralized settlement exposes a critical structural dilemma regarding capital distribution. If frictionless access to perpetual futures merely replaces fundamental underwriting with zero-sum volatility loops, open architecture risks morphing the price discovery mechanism into an accelerated digital casino.
Legacy exchange defenses against permissionless liquidity
The rapid growth of on-chain perpetual futures executing on dedicated consensus layers forced traditional equity bourses to re-evaluate their restrictive clearing hours. Processing billions of dollars in daily volume without centralized clearinghouses demonstrates that programmatic settlement significantly reduces overhead costs. Automated order book execution matches trades in sub-second intervals, challenging the historic fee structures maintained by conventional brokerages.
This operational pressure led the New York Stock Exchange to initiate regulatory filings seeking approval for twenty-two-hour daily equity trading sessions. Official documentation from the Securities and Exchange Commission confirms that legacy institutions must engineer uninterrupted trading access to prevent structural capital migration toward decentralized protocols.
This technical adoption validates institutional integration of financial automation, proving that programmatic clearing improves operational speed across the broader market. Yet faster operational speed does not automatically safeguard non-professional participants against sudden liquidity shocks.
Algorithmic settlement efficiency versus perpetual liquidation models
Proponents of decentralized finance argue that public ledger auditability creates fair market conditions by dismantling preferential early-stage access tiers. By removing centralized underwriting hurdles, participants can deploy advanced hedging and synthetic derivative strategies without seeking approval from bank compliance desks or institutional prime brokers.
Conversely, market microstructure data indicates that continuous perpetual leverage predominantly rewards high-frequency trading groups and automated market makers. In ecosystems governed by dynamic hourly funding rates and automated liquidations, retail participants routinely absorb outsized downside risks. Research from the Bank for International Settlements indicates that retail market participants on decentralized networks experience persistent net losses when executing against specialized algorithmic counterparties that extract value on-chain.
Market fundamentalists counter that price volatility represents the authentic cost of participating in systems devoid of discretionary administrative bailouts. Under this view, protocol infrastructure exists solely to process transactions deterministically, without paternalistic mandates to shield individual traders from capital drawdowns.
This counter-perspective would lose validity if decentralized clearing engines require manual administrative intervention or chain reorganizations during severe liquidation cascades. If removing financial intermediaries merely transfers execution premiums to sophisticated arbitrageurs while non-professional balances are consistently drained, the goal of open capital access remains unrealized.
If decentralized derivative volumes expand over successive market cycles while long-term retail capital preservation rates fall below those observed in traditional equity indices, empirical evidence will confirm that perpetual trading architecture functions primarily as an accelerated capital transfer mechanism benefiting high-frequency liquidity providers.
This article is for informational purposes only and does not constitute financial advice.