Bitcoin may be blue chip collateral but is every tokenized alternative truly secure
Considering base assets as prime collateral in decentralized finance exposes a critical divergence when bridged to secondary networks. Custody introduces severe structural risks that the research from Circle on credit market structure demonstrates with institutional precision.
Today, decentralized lending protocols accept diverse synthetic representations of Bitcoin under uniform liquidation metrics. This design treats base-layer cryptographic settlement as equivalent to third-party redemption IOUs, ignoring the profound counterparty and legal dependencies inherent in bridged architectures.
The peer-to-peer design articulated in the foundational Bitcoin whitepaper by Satoshi Nakamoto in 2008 established electronic cash free of financial intermediaries. Base-layer security depends entirely on verifiable proof-of-work consensus, which eliminates reliance on trusted external custodians or central gatekeepers.
Conversely, bridged token derivatives transfer value across foreign execution layers using smart contracts. This mechanism replaces absolute monetary immutability with multi-signature committees, corporate custodians, and institutional vault administrators that hold the underlying reserves off-chain.
The formal architecture established in the wrapped tokens technical specification confirms that WBTC relies on a closed consortium of authorized merchants and designated custodians. Minting and burning require institutional validation, subordinating decentralized liquidity to the operational continuity of regulated corporate custodians.
If a custodian faces regulatory freezing orders or commercial bankruptcy, circulating synthetic tokens lose parity immediately. Consequently, the broader market cannot treat wrapped derivatives as direct collateral equivalents without factoring in substantial custodial discount rates.
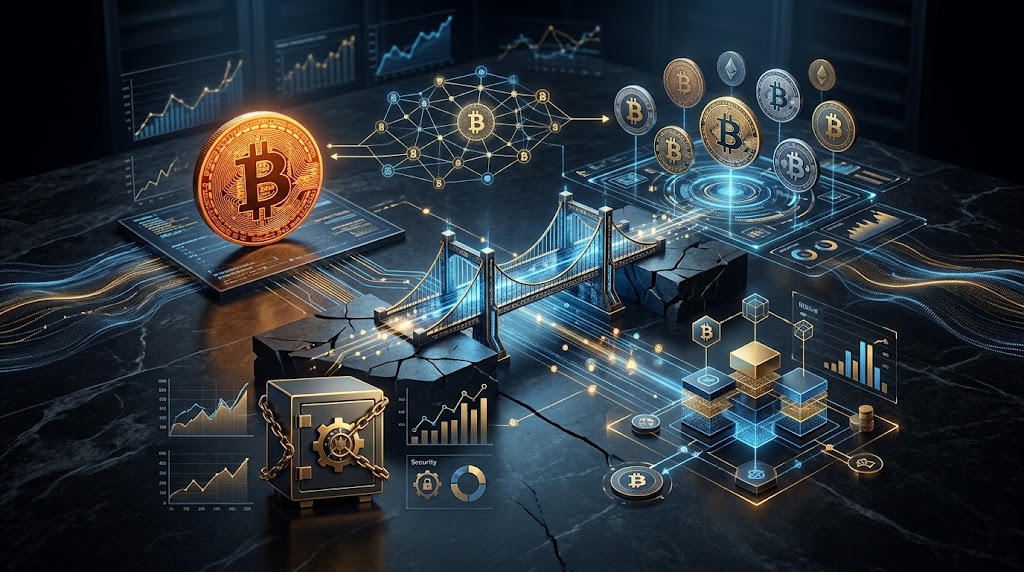
Structural divergence between native assets and synthetic wrapped representations
Cross-chain bridge architectures represent another persistent vector of systemic risk documented in the Ethereum bridge architecture documentation. Locking native reserves on one blockchain to mint claims on another creates a centralized honeypot that has repeatedly suffered technical exploitation across decentralized finance protocols.
Historical losses prove structural vulnerabilities across decentralized protocols, notably when cross-chain bridges like Ronin and Wormhole suffered multi-hundred-million-dollar breaches between 2021 and 2022. In these instances, synthetic representations plummeted below nominal values because underlying collateral was systematically drained from smart contracts.
Unlike native proof-of-work settlement, where independent node operators validate every transaction, wrapped tokens permit opaque balance-sheet practices. Certain issuers back secondary representations with debt obligations or yield-bearing collateral instead of maintaining verifiable, one-to-one verifiable on-chain reserves.
During extreme volatility events, peg dislocations trigger cascading liquidations within automated money markets. Borrowers pledging wrapped collateral incur automated liquidations when token prices diverge on decentralized exchanges, regardless of whether spot prices on base settlement networks remain stable.
Protocol governance introduces further operational unpredictability. Upgrades to multi-signature parameters, migration of administrative keys, or jurisdictional relocations by custodians can unilaterally alter redemption rights without the consent of secondary token holders.
Over a dozen wrapped representations currently circulate across alternative execution environments, representing billions of dollars in gross value. Yet fewer than ten percent implement real-time cryptographic attestations or automated reserve verification mechanisms directly into collateral monitoring engines.
Counterparty assessments and operational horizons for institutional lending solvency
Proponents of tokenized credit offer a pragmatic counterargument rooted in capital efficiency. Confining native assets exclusively to layer-one storage renders hundreds of billions of dollars in potential collateral economically idle, starving decentralized debt markets of high-quality liquid assets.
Under this view, regulated custody, proof-of-reserve standards, and third-party insurance frameworks adequately neutralize default probabilities. Moreover, prominent implementations like WBTC have processed billions in redemptions across multiple market downturns over half a decade without operational insolvency.
Decentralized infrastructure is evolving rapidly through emerging cryptographic innovations like BitVM and trust-minimized multi-party computation. If these mechanisms successfully verify cross-chain state transitions without relying on custodial intermediaries, the structural gap between native and tokenized collateral would effectively dissolve.
Until trustless architectures achieve production maturity, counterparty divergence remains a structural reality. Conflating bridged derivatives with base-layer assets represents a fundamental mispricing of liquidity and solvency risks in institutional lending portfolios.
Decentralized credit protocols must recalibrate collateral risk frameworks by implementing dynamic loan-to-value discounts for synthetic assets. Assuming frictionless redemption during crisis scenarios ignores historical liquidity freezes observed across centralized and decentralized finance.
Regulatory authorities in major jurisdictions are concurrently intensifying oversight of bridge custodians and token issuers. Enhanced identification mandates and transaction monitoring requirements threaten to segment liquidity, restricting seamless cross-chain arbitrage during periods of acute stress.
Blue-chip collateral fundamentally requires sovereign finality, zero counterparty liability, and deep programmatic liquidity. While native layer-one transactions fulfill these requirements via distributed consensus, tokenized derivatives remain contractual IOUs subject to technological, legal, and operational failure modes.
Institutional debt markets will inevitably segregate capital allocations based on these exact risk demarcations. Conservative asset managers will favor segregated custodial architectures over wrapped representations exposed to multi-signature and smart contract vulnerabilities.
Credit spreads will widen substantially as institutional risk engines begin pricing wrapper risks independently from native assets. If an on-chain custodian suffers regulatory seizure or insolvency within the next twenty-four months, borrowing spreads between native and wrapped collateral will exceed two hundred basis points.
Conversely, if trust-minimized, non-custodial bridges capture more than fifty percent of total wrapped volume, derivative risk premiums will compress toward negligible levels. Tracking this spread dynamic will reveal whether decentralized lending achieves systemic maturity or succumbs to traditional rehypothecation fragilities.
This article is for informational purposes only and does not constitute financial advice.