Why PNC Bank Uses Stablecoins as Modernized SWIFT Rails While Rejecting Crypto Custody
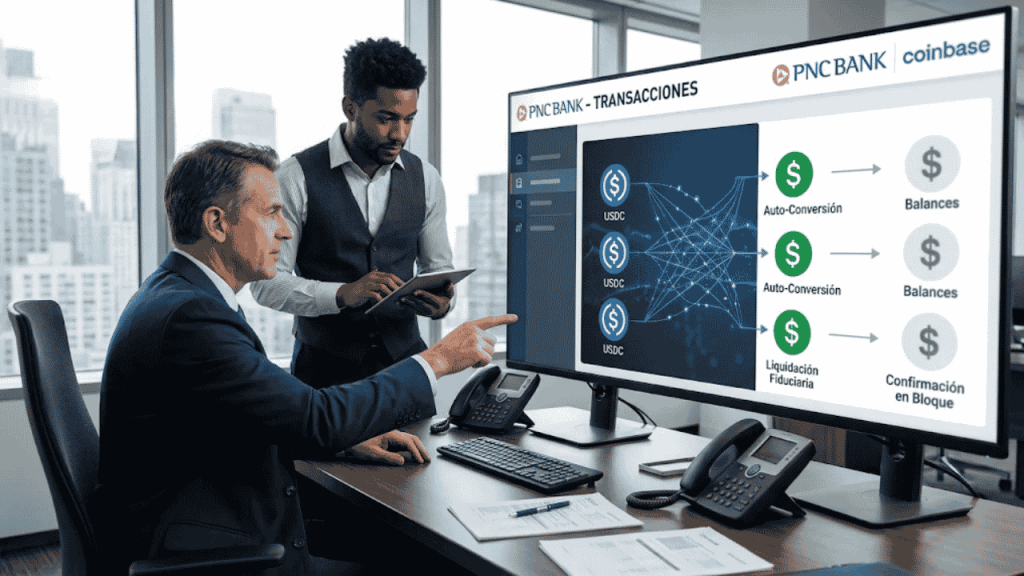
PNC Bank’s pilot project alongside Coinbase to settle corporate client receivables using USD Coin (USDC) does not represent an institutional capitulation to decentralized finance. Rather than endorsing self-sovereign monetary architecture, large banks reject direct custody of digital assets as demonstrated across filings published by the Federal Reserve Board large commercial releases.
Industry observers frequently celebrate these institutional agreements as evidence of mainstream integration. However, the operational reality is that the bank converts incoming tokens into conventional fiat balances immediately upon confirmation, eliminating balance sheet exposure and reducing distributed networks to a convenient messaging mechanism.
PNC Bank ranks among the top commercial lenders in the United States, managing total consolidated assets exceeding 560 billion dollars. Its technical partnership with Coinbase aims to accelerate payment clearing for enterprise clients while eliminating exchange volatility from institutional balance sheets entirely.
This defensive operational pattern is not an isolated experiment. It replicates the strategy observed when US banks enable direct crypto purchases through regulated third-party brokers, insulating depository accounts from balance sheet risk and regulatory scrutiny regarding balance sheet capital adequacy.
The scale of the dollar token market explains this institutional engagement. Circulating supplies of dollar-pegged assets currently exceed 190 billion dollars across public blockchains according to the DefiLlama stablecoins dashboard, with USDC accounting for more than 35 billion dollars in active circulation.
The underlying collateral backing these tokens provides the legal security required by risk management committees. The monthly reserve breakdowns compiled in Circle monthly attestation reports demonstrate that reserves consist of short-term Treasury securities and cash, delivering the balance sheet safety that unpegged crypto assets cannot offer.
The corporate cooptation of decentralized communication rails
Historically, commercial banking institutions do not invent communication highways; they coopt them once stability is proven. When lenders established the SWIFT consortium in 1973, banks did not redesign fractional reserve lending, but rather replaced telex machinery to settle correspondent obligations faster across borders.
Half a century later, a parallel institutional playbook is unfolding. Ethereum functions as an auxiliary settlement rail, allowing corporate treasuries to finalize payments in seconds without maintaining costly bilateral balances across foreign correspondent accounts.
Processing institutional volumes requires rigorous compliance controls at the gateway level. For this reason, centralized liquidity hubs adapt as tokenized assets gain massive transaction volumes under strict compliance frameworks, eliminating non-compliant assets to satisfy regulatory oversight in major financial markets.
Regulatory frameworks strictly discourage commercial banks from carrying direct digital asset risk. The policy report issued by the President Working Group report on stablecoins mandates that stablecoin payment arrangements must adhere to prudential rules matching those applied to federally insured commercial banks.
Under such regulatory supervision, auto-conversion provides a mandatory defensive firewall. Lenders neutralize digital asset exposure during the execution block, transforming an open public system into a private transit mechanism that deposits familiar fiat liabilities into regulated corporate accounts.
Supporters of enterprise blockchain adoption argue that this initiative validates the resilience of distributed ledgers. They emphasize that commercial participation expands institutional liquidity, reduces clearing fees for global corporations, and normalizes smart contract execution across conservative boardrooms.
That defense carries weight regarding software maturity and network bandwidth. However, it mistakes transaction routing for deep monetary adoption: using smart contracts to transfer dollar claims does not mean commercial banks accept crypto assets as sovereign value or accounting units.
The structural barrier between payment transport and custody
The foundational thesis of decentralized networks depends on trustless settlement and non-custodial balance ownership. When corporations use USDC strictly as a temporary settlement pipeline to receive commercial bank deposits, traditional banks retain their lucrative custody monopolies.
Under this operational design, decentralization becomes a transport utility while regulated lenders preserve full control over corporate deposits. Decentralized validators assume computational network costs, while traditional institutions maintain client relationships, credit creation authority, and legal custody.
Network performance characteristics present additional operational challenges for institutional users. During periods of sharp network congestion, base-layer transaction costs can spike unpredictably, prompting corporate treasurers to evaluate private permissioned ledgers or compliant Layer-2 settlement channels instead.
A genuine transformation will occur only when prudential regulators permit commercial banks to retain stablecoin inventories overnight. If corporate balance sheets begin accumulating dollar tokens across multiple fiscal reporting periods without fiat conversion, this cooptation thesis will require structural revision.
If over the next twenty-four months annual USDC volumes processed by PNC Bank surpass 10 billion dollars while fiat auto-conversions remain above 99%, empirical data will confirm that banks have converted public networks into a low-cost alternative to traditional correspondent rails without relinquishing financial power.
This article is for informational purposes and does not constitute financial advice.