Best crypto exchanges for beginners DEX vs CEX: which truly protects assets?
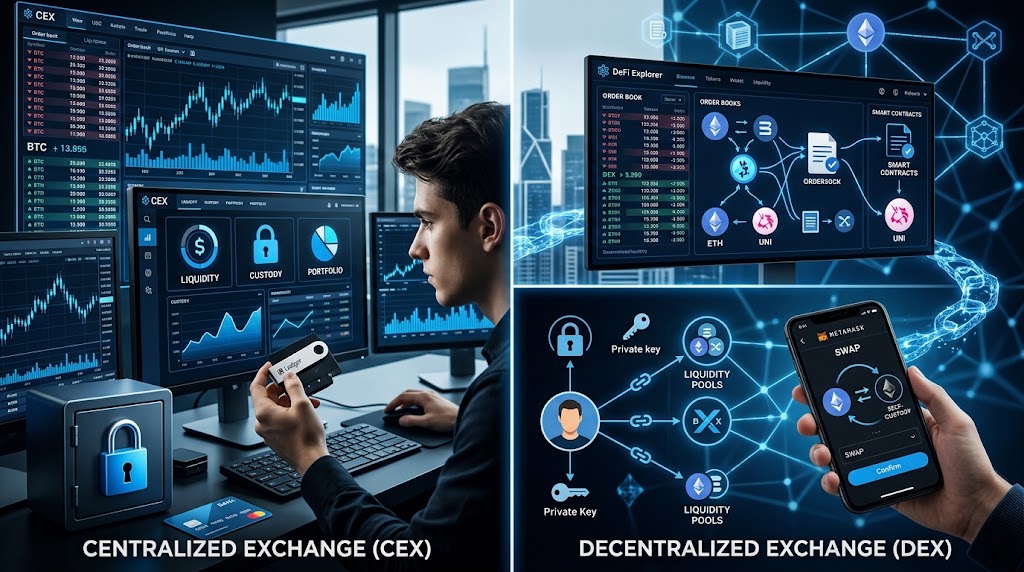
Selecting a trading venue represents the initial operational hurdle for newcomers exploring digital assets. At this early stage, delegated custody neutralizes financial autonomy against explicit warnings highlighted in the official Investor.gov alert regarding the total absence of federal deposit insurance on exchange balances.
Conventional retail guidance suggests that novices must remain confined to centralized platforms due to interface simplicity. However, storing static balances on private custodial servers recreates the identical structural vulnerabilities of fractional banking that crypto assets were architected to overcome.
This trade-off requires immediate evaluation because Layer 2 networks have radically suppressed transaction expenses. Gas costs incurred across decentralized smart contracts no longer constitute an exclusionary economic wall for traders deploying modest initial capital reserves.
Among centralized venues, platforms like Coinbase and Kraken excel by delivering intuitive navigation tools alongside direct banking payment rails. Nevertheless, the Coinbase Form 10-K filing acknowledges that customer custodial assets could be legally treated as bankruptcy estate property during insolvency proceedings.
This legal reality confirms that centralized exchanges assume user liabilities rather than conferring cryptographic property rights. If an intermediary platform suspends outgoing transfers, the account holder is legally classified as an unsecured creditor in court.
Market history confirms the destructive potential of this corporate custody approach. The collapse of Mt. Gox in 2014 resulted in 850,000 missing bitcoins, while the bankruptcy of FTX in 2022 produced an 8.9 billion dollar balance deficit for depositors.
The operational illusion of account balances
Viewing account balances within Binance or Kraken apps generates a deceptive sense of ownership. Those numbers merely reflect internal ledger entries in private databases rather than verifiable claims recorded on a transparent, distributed public ledger.
In contrast, decentralized protocols execute peer-to-peer asset swaps without seizing custody of user funds. This on-chain settlement model gained momentum as Uniswap leads recent DEX volume across market analytics dashboards, processing billions in recurring trade turnover.
For beginners entering decentralized finance, Uniswap remains the standard benchmark due to its uncluttered interface. Concurrently, Aerodrome has established itself as the leading venue on Base, offering optimized order routing and negligible gas fees.
These protocols operate autonomously via deterministic smart contracts without human broker intervention. As documented in the Uniswap v3 Core whitepaper, concentrated liquidity reduces execution fees and price slippage, enabling private traders to execute spot transactions while retaining complete control over private keys.
Configuring noncustodial software wallets such as Rabby or MetaMask demands procedural diligence, yet eliminates counterparty risk. When operating on Layer 2 rollups like Base or Arbitrum, swaps confirm within seconds for cents, making self-custody accessible to retail users.
The viability of this architecture is highlighted when Aerodrome captures dominant Base volume, processing the majority of on-chain trading activity. This operational milestone proves that deep market liquidity is no longer exclusive to centralized corporate intermediaries.
Centralized exchanges frequently charge hidden spread markups reaching 1.5% on simple convert features. Conversely, decentralized pools maintain transparent fee tiers between 0.05% and 0.3%, protecting the net purchasing power of beginner account balances from day one.
Operational friction versus counterparty solvency
The argument favoring centralized exchanges legitimately highlights that self-custody introduces significant user friction. Losing a recovery seed phrase or signing an unverified smart contract approval can extinguish user capital permanently without recourse to administrative support.
This human vulnerability is substantiated by industry research. According to the Chainalysis Crypto Crime Report, compromised private keys and user security mistakes caused substantial capital losses, proving that human error penalizes self custody just as severely as corporate exchange bankruptcies.
The critical divergence lies in the structural nature of the risk. Centralized counterparty failure is opaque, systemic, and unavoidable for the user; conversely, self-custody operational risks can be effectively minimized through methodical security habits and hardware verification.
This analytical thesis would be invalidated if centralized exchanges introduced fully segregated legal trusts audited in real-time, accompanied by government-backed deposit insurance funds covering one hundred percent of user assets during corporate liquidation events.
Under existing international regulations, no centralized cryptocurrency exchange provides comprehensive legal deposit guarantees. Platform terms of service systematically transfer all balance sheet insolvencies onto the retail customer during severe liquidity shortfalls.
The pragmatic strategy for new market participants combines the distinct functional benefits of both environments. Centralized exchanges should function strictly as conversion ramps from fiat currencies, after which prompt withdrawal preserves capital integrity within self-hosted wallets.
Once assets reside in self-custody, decentralized exchanges like Uniswap or Aerodrome permit continuous spot trading without requiring permission from a corporate entity, insulating investor balances from arbitrary account freezes or regulatory holds.
If the rollout of account abstraction standards across consumer wallets maintains its trajectory while secondary layer fees remain below five cents, non-fiat decentralized spot trading volume will outpace centralized alternatives over the next twenty-four months.
This article is for informational purposes and does not constitute financial advice.